Mortgage interest rates in Chile: how they have changed and what each bank offers
Mortgage interest rates in Chile averaged 4.07% in September, well below the 5.21% of late 2023, but they have risen for four months. What each bank offers, according to the CMF.
· 5 min read
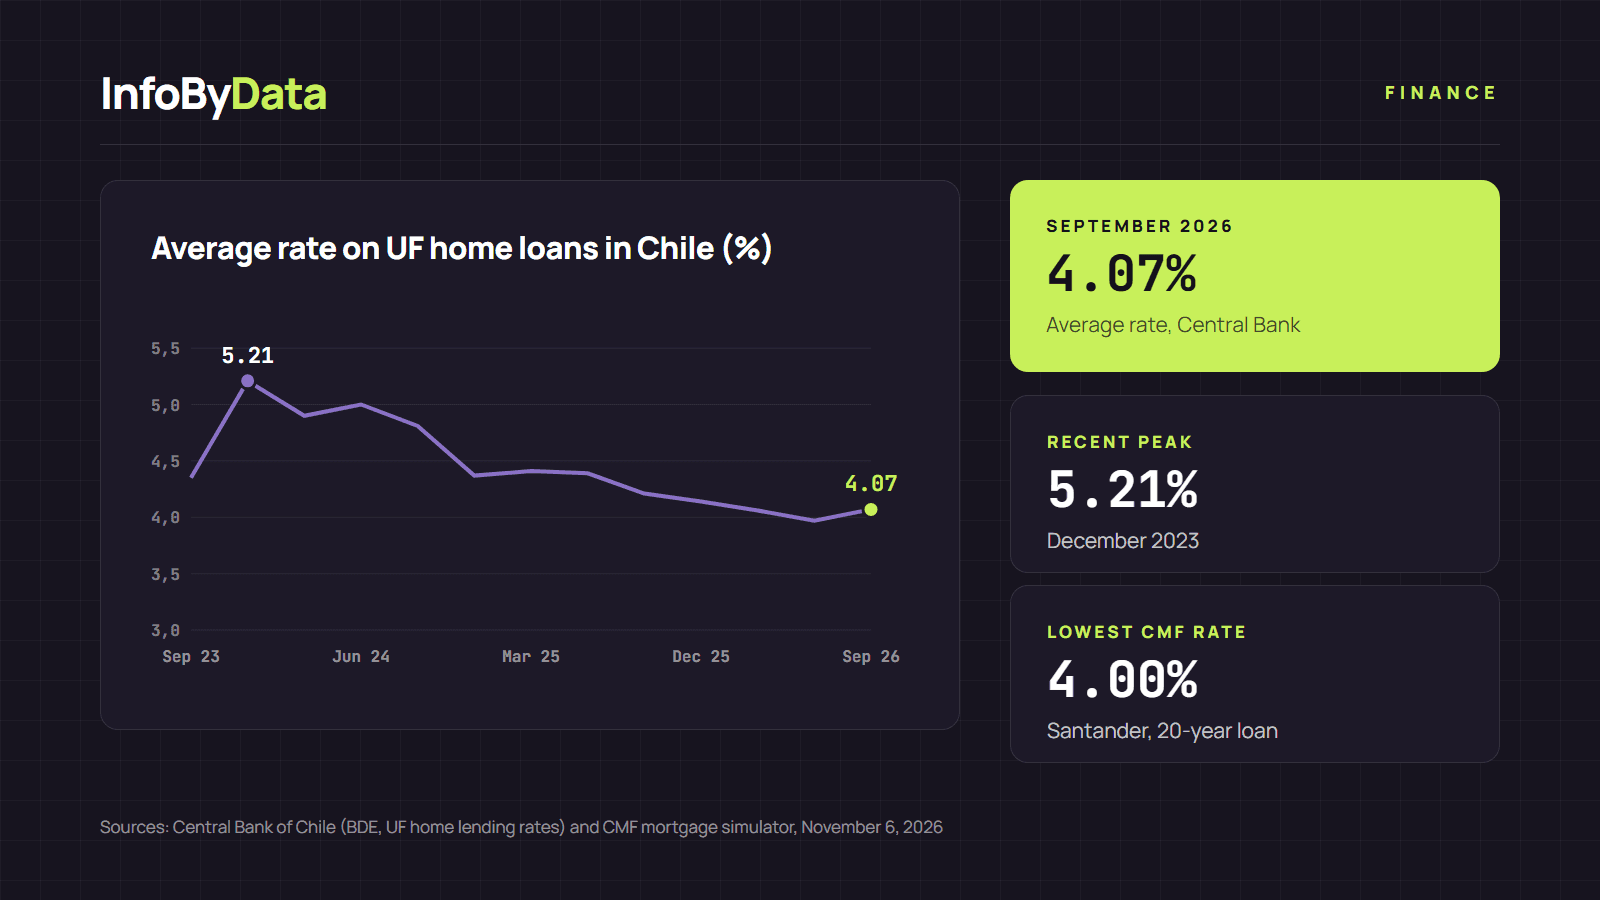
Mortgage interest rates in Chile averaged 4.07% in September 2026 for UF-denominated home loans, according to the Central Bank of Chile's Statistics Database. That is more than a point below the 5.21% of December 2023, the highest level in the past three years. But the decline has stalled: the rate hit its low in May (3.96%) and has risen for four months in a row. Here is how rates have changed and what each bank offers today.
4.07%
Average rate in September
UF home loans
5.21%
Recent peak
December 2023
4.00%
Lowest rate reported to the CMF
20-year loan
Source: Central Bank of Chile, UF home lending rates and CMF mortgage simulator, November 6, 2026
View the data as a table
| Average rate in September | 4.07% | UF home loans |
| Recent peak | 5.21% | December 2023 |
| Lowest rate reported to the CMF | 4.00% | 20-year loan |
How mortgage interest rates in Chile have changed
Mortgage interest rates in Chile rose sharply in 2022 and 2023, when the Central Bank raised its policy rate to curb inflation. In December 2023 they reached 5.21%. From there they fell almost without pause for two and a half years, down to 3.96% in May 2026.
Source: Central Bank of Chile, Statistics Database, UF-adjusted home lending rates
View the data as a table
| Sep 23 | 4.35% |
| Dec 23 | 5.21% |
| Mar 24 | 4.9% |
| Jun 24 | 5% |
| Sep 24 | 4.81% |
| Dec 24 | 4.37% |
| Mar 25 | 4.41% |
| Jun 25 | 4.39% |
| Sep 25 | 4.21% |
| Dec 25 | 4.14% |
| Mar 26 | 4.06% |
| Jun 26 | 3.97% |
| Sep 26 | 4.07% |
Since June, the trend has turned: 3.97% in June, 4.00% in July, 4.04% in August and 4.07% in September. The increases are small, but they break a streak of declines. For perspective, the Central Bank series, which starts in 2009, hit its low in October 2019 at 1.99%. Today's rates are about twice that level.
More loans than last year
Even though rates are no longer falling, banks are granting more home loans. In September 2026 they issued CLP 560.8 billion in new UF mortgage loans, the highest monthly amount since November 2021, according to the same Central Bank table (in pesos of each month, not adjusted for inflation). From January to September the total reached CLP 4.48 trillion, 15% more than in the same period of 2025. Earlier this month, InfoByData reported that banks are easing their lending conditions and demand is picking up.
What types of mortgage are available
Before comparing rates, it helps to know what you are comparing. According to CMF Educa, there are three types of rate for a mortgage in Chile:
- Fixed rate: it stays the same for the whole loan. The payment in UF does not change. This is the most common option.
- Variable rate: it is adjusted periodically according to a reference rate. It can go down or up.
- Mixed rate: it is fixed for the first few years and then becomes variable.
The lender also matters. A non-endorsable mortgage loan (mutuo no endosable) is granted by a bank and stays with the bank. An endorsable mortgage loan (mutuo endosable) can be sold to another institution, such as an insurance company. The CMF notes that each type of loan has different costs if you want to pay it off early.
Mortgage interest rates in Chile by bank
The CMF runs a mortgage simulator with the offers the banks themselves report. We queried it on November 6, 2026 for a UF 3,000 loan over 20 years, using the format the CMF applies for comparison: a non-endorsable, fixed-rate loan in UF.
| Bank | Rate | CAE | Payment with insurance |
|---|---|---|---|
| Santander | 4.00% | 4.62% | CLP 785,549 |
| BancoEstado | 4.55% | 4.83% | CLP 797,520 |
| Banco Internacional | 4.68% | 5.02% | CLP 808,666 |
| BCI | 4.94% | 5.02% | CLP 809,904 |
| Bice | 4.90% | 5.06% | CLP 811,968 |
| Coopeuch | 4.80% | 5.07% | CLP 811,555 |
| Banco de Chile | 4.78% | 5.10% | CLP 813,206 |
| Banco Falabella | 4.68% | 5.17% | CLP 816,509 |
| Scotiabank | 4.73% | 5.50% | CLP 842,515 |
| Itaú | 5.02% | 5.58% | CLP 847,881 |
The CMF ranks banks by CAE (carga anual equivalente, the equivalent annual cost), which combines the rate, insurance and loan fees. That is why the order does not match the rate: Banco Falabella has a 4.68% rate, the same as Banco Internacional, but a higher CAE. Scotiabank offers a 4.73% rate and reaches a 5.50% CAE.
Read these figures carefully: each bank updates its information whenever it chooses. Bice's figures are from October 28, 2025 and Banco Falabella's from December 30, 2024, so they may not reflect their current offer. The CMF also warns that these are reference rates, without any assessment of your situation.
The average and the offers are not the same
The Central Bank's average rate (4.07%) is lower than almost every offer reported to the CMF. That is not a contradiction: the average includes loans with different terms and amounts, and many customers negotiate lower rates, for example if they already have a checking account with the bank. The CMF clarifies that its simulator does not include such agreements or promotions.
How much your payment changes with the rate
Half a point may not sound like much, but you will notice it. Using InfoByData's mortgage simulator, we calculated a UF 3,200 loan over 25 years, without insurance, at the UF value of November 6 (CLP 41,279.51):
- At the December 2023 rate (5.21%), the payment would be UF 19.10, about CLP 788,000 a month.
- At the September 2026 rate (4.07%), it drops to UF 17.01, about CLP 702,000 a month.
The difference is almost CLP 86,000 a month, and more than UF 600 in interest over the life of the loan.
If you are buying a new home, you can also apply for the rate subsidy, which lowers the rate by up to 60 basis points under Law 21,748. Law 21,836, from August 2026, extended it to homes worth up to UF 6,000 and to 80,000 subsidies, until May 31, 2028. We explain the details in what changed with the subsidy expansion.
What it means for you
- Mortgage interest rates in Chile are no longer falling. If you were waiting for lower rates to buy, the last four months show slight increases. Nobody knows where they will go next, so it makes sense to decide based on what you can afford, not on a bet about rates.
- Compare the CAE, not just the rate. Between the cheapest and the most expensive offer in the CMF simulator there is a CLP 62,332 monthly difference on a 20-year loan. Ask several banks for a written quote and compare them in our mortgage simulator.
- Negotiate. The rates reported to the CMF are standard. Your bank may offer you a better one if you have other products with it or a good track record. This article is for information only and is not financial advice.
Sources
- Central Bank of Chile, Statistics Database: average UF-adjusted home lending rates and amounts granted (September 2026 data)
- CMF, mortgage simulator (queried on November 6, 2026)
- CMF Educa, mortgage loans
- CMF Educa, how to compare mortgage options
- Law 21,748, Official Gazette of May 29, 2025
- Law 21,836, BCN
- mortgage interest rates in Chile
- mortgage rate
- home loan
- CAE
- banks
- Central Bank of Chile
- CMF