Is it better to rent or buy a home in Chile? An analysis with 2026 rates
Is it better to rent or buy? With the mortgage rate at 4.07%, 63% of the payment goes to interest in the first year of a 25-year loan. How to run the numbers for your case.
· 4 min read
Is it better to rent or buy a home? It depends less on the saying "renting is throwing money away" and more on one calculation: how much of what you pay each month never comes back to you. With the average mortgage rate for September 2026 (4.07%, according to the Central Bank of Chile), 63% of the payment goes to interest in the first year of a 25-year loan. Here is how to compare both options with your own numbers.
UF 17.01
Monthly payment
about CLP 702,000
63%
Interest in the first year
of the total paid that year
UF 1,904
Interest over the whole loan
60% of the amount borrowed
Source: InfoByData calculation using the Central Bank average rate (September 2026) and the UF on November 6, 2026. UF 3,200 loan over 25 years, without insurance
View the data as a table
| Monthly payment | UF 17.01 | about CLP 702,000 |
| Interest in the first year | 63% | of the total paid that year |
| Interest over the whole loan | UF 1,904 | 60% of the amount borrowed |
Rent or buy: what you are comparing
When you rent, the whole rent is an expense: you get nothing back. When you buy with a mortgage, the payment has two parts:
- Principal: the part that reduces your debt. It works like savings, because it increases the share of the home you own.
- Interest: what you pay the bank for the loan. Like rent, you do not get it back.
So, to know whether it is better to rent or buy, you should not compare the rent with the full payment, but with the part of the cost of buying that you do not recover: interest, insurance, property tax, maintenance and purchase costs. And add something people often forget: what you stop earning on your down payment.
How much of your payment is interest
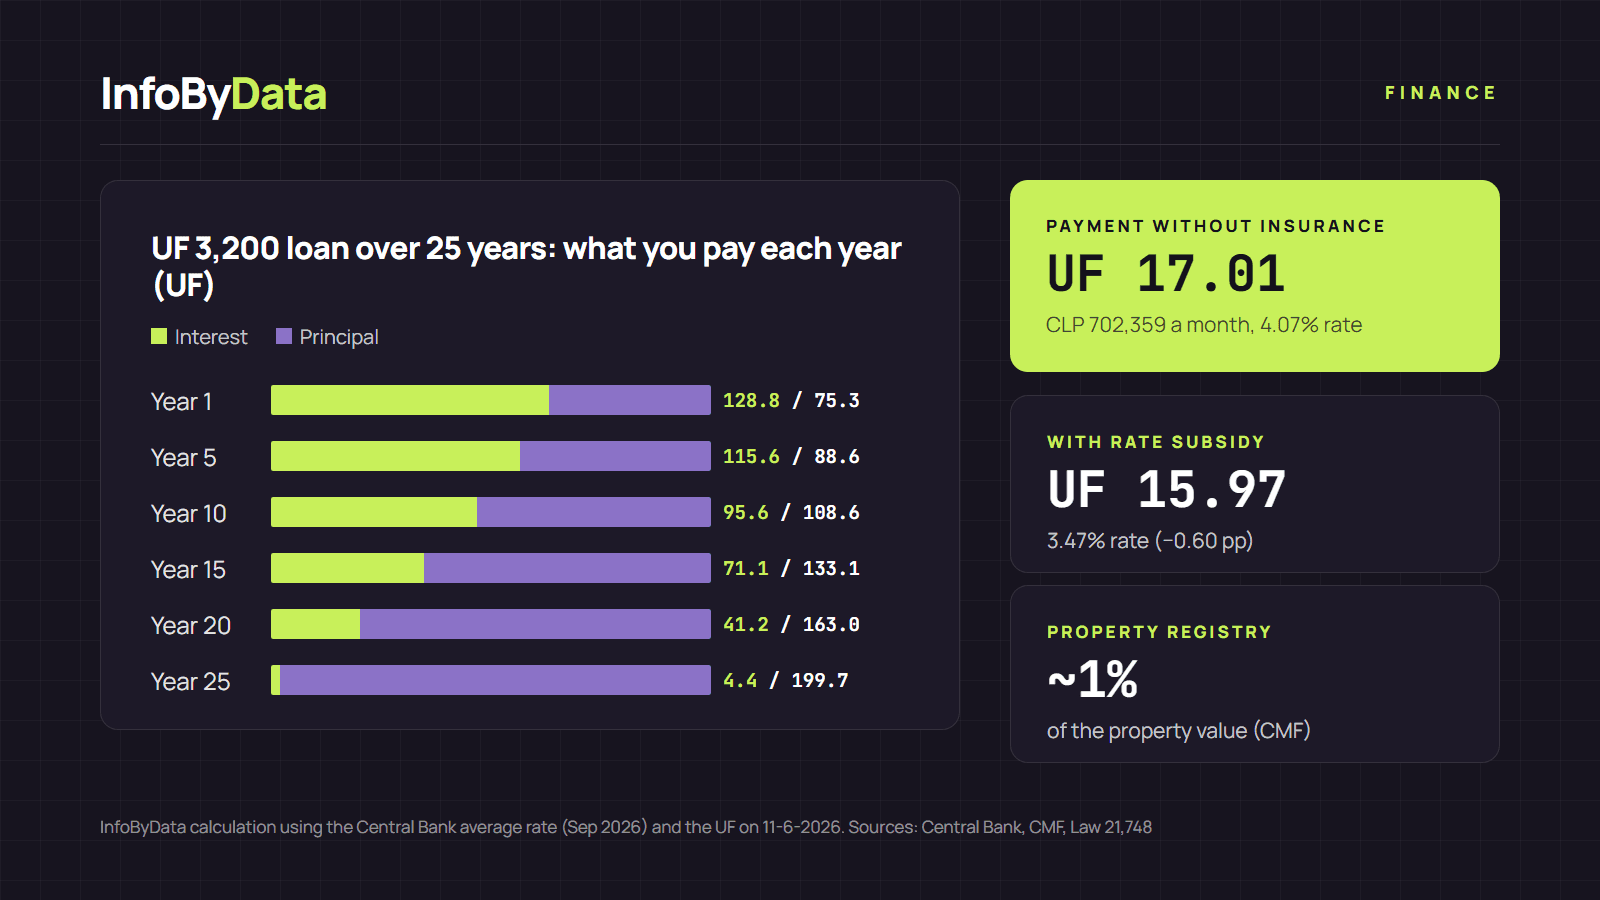
Take an example: a home worth UF 4,000, with a 20% down payment (UF 800) and a UF 3,200 loan over 25 years, at the average rate of 4.07%. We calculated it with InfoByData's mortgage simulator.
- Interest
- Principal
Source: InfoByData calculation with a fixed payment and a 4.07% annual rate (Central Bank, September 2026)
View the data as a table
| Interest | Principal | |
|---|---|---|
| Year 1 | 128.8 UF | 75.3 UF |
| Year 5 | 115.6 UF | 88.6 UF |
| Year 10 | 95.6 UF | 108.6 UF |
| Year 15 | 71.1 UF | 133.1 UF |
| Year 20 | 41.2 UF | 163 UF |
| Year 25 | 4.4 UF | 199.7 UF |
The payment is always the same (UF 17.01 a month, about UF 204 a year), but its makeup changes. In the first year you pay UF 128.8 in interest, about CLP 443,000 a month. Only in year 9 does principal overtake interest. By the end, you will have paid UF 1,904 in interest, 60% of what you borrowed.
The hidden cost: the down payment
To buy, in this example you put down UF 800, about CLP 33 million. If you rent, that money can stay invested and earn a return. This is called opportunity cost. If, for example, that money earned 3% a year above inflation (a hypothetical figure), you would give up UF 24 a year, about CLP 83,000 a month.
Then there are the purchase costs. According to the CMF, they include stamp tax, notary fees, the appraisal, the title review and registration with the Property Registry (Conservador de Bienes Raíces), which alone costs about 1% of the property value. Banks also require life (desgravamen) and fire insurance.
An example of the full calculation
Assume a hypothetical rent of UF 15 a month (about CLP 619,000) for a home similar to the one in the example. It is an illustrative figure: rents vary a lot by neighborhood and type of property.
| First year, per month | Buy | Rent |
|---|---|---|
| Mortgage interest | UF 10.7 | — |
| Opportunity cost of the down payment (hypothetical 3%) | UF 2.0 | — |
| Rent (hypothetical) | — | UF 15.0 |
| Cost you do not recover | UF 12.7 + insurance, maintenance and property tax | UF 15.0 |
In this example, buying costs somewhat less per month than renting, but the edge is narrow and can flip: insurance, maintenance, property tax and purchase costs all add up on the buying side. Also, the buyer pays a UF 17.01 monthly installment (plus insurance), more than the rent, and needs the down payment saved.
There is another factor: the price of the home. If it rises faster than inflation, buying wins; if it stagnates, renting wins. Nobody can know for sure.
When it is better to rent or buy
There is no single answer, but there are clear signs:
- Buying may make sense if you plan to stay many years in the same city, you have already saved the down payment and costs, and the payment with insurance fits comfortably in your budget. The longer you stay, the more the purchase costs are spread out and the more each payment goes to principal.
- Renting may make sense if you could move cities or jobs within a few years, you have not yet saved the down payment, or the payment would leave you no room for emergencies. Buying and selling within a short time is usually expensive because of the costs of each transaction.
- The rate matters. At the December 2023 rate (5.21%), the same loan would have a payment of UF 19.10 and you would pay UF 165 in interest in the first year, 28% more than today. We show how mortgage interest rates in Chile have changed.
If you buy a new home worth up to UF 6,000, the rate subsidy can lower your rate by up to 0.60 points, under Law 21,748. In the example, the payment would fall from UF 17.01 to UF 15.97.
What it means for you
- Compare what you do not recover. To know whether it is better to rent or buy, compare the rent with interest, insurance, property tax, maintenance and the opportunity cost of the down payment, not with the full payment.
- Run the numbers with your own figures. Enter the home value, your down payment and the rate your bank offers in the mortgage simulator, and see how much interest you pay each year in the amortization table.
- Think about how long you will stay. Buying usually pays off more the longer you live in the same property. This article is for information only and is not financial advice.
Sources
- Central Bank of Chile, Statistics Database: average UF-adjusted home lending rates (September 2026)
- CMF Educa, what costs does a mortgage involve?
- Law 21,748, Official Gazette of May 29, 2025
- InfoByData calculations with a fixed payment (French amortization), a monthly rate equal to the annual rate divided by 12 and a UF of CLP 41,279.51 (November 6, 2026, SII). The rent and the return on the down payment are hypothetical figures.
- better to rent or buy
- renting
- buying a home
- mortgage
- monthly payment
- opportunity cost