Prepaying or refinancing a mortgage in Chile: how much the bank charges and when it pays off
Refinancing a mortgage can cut the monthly payment by over CLP 70,000. How much the bank charges for prepaying, what the law says and when it pays off.
· 4 min read
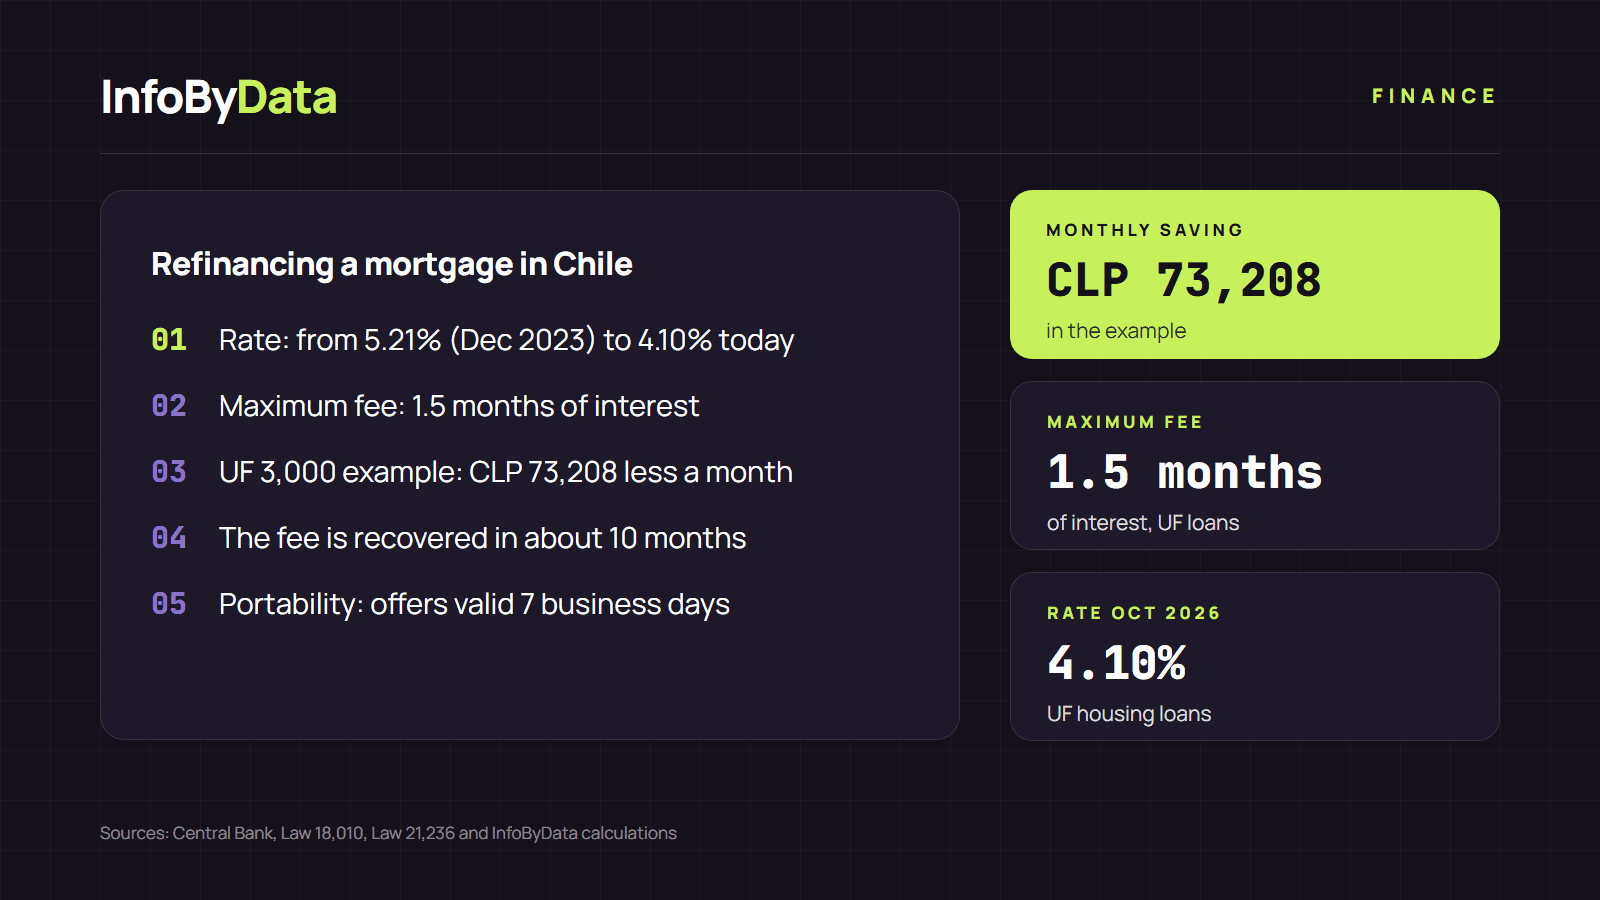
If you took out a home loan between late 2023 and 2024, you probably pay a higher rate than today's. The average rate on UF mortgages reached 5.21% in December 2023 and was 4.10% in October 2026, according to the Central Bank. That gap can make refinancing a mortgage worthwhile: replacing it with a new, lower-rate loan at the same bank or another one.
In this article we explain how much the bank can charge you for paying early, how much you could save and how to tell whether it pays off.
5.21%
Average rate in December 2023
UF housing loans
4.10%
Average rate in October 2026
1.11 points lower
CLP 73,208
Monthly saving in the example
per month
1.5 months
Maximum prepayment fee
of interest, on UF loans
Source: Central Bank, Law 18,010 and InfoByData calculations with the UF of November 12, 2026
View the data as a table
| Average rate in December 2023 | 5.21% | UF housing loans |
| Average rate in October 2026 | 4.10% | 1.11 points lower |
| Monthly saving in the example | CLP 73,208 | per month |
| Maximum prepayment fee | 1.5 months | of interest, on UF loans |
How much the bank can charge for prepaying
Prepaying means paying off the loan, or part of it, before the end of the term. That is what happens when you refinance: the new loan pays off the old one. Law 18,010 sets a cap in its article 10 on what the bank can charge for that, for loans of up to 5,000 UF:
| Type of loan | Maximum prepayment fee |
|---|---|
| Indexed to the UF (like most mortgages) | 1.5 months of interest on the amount you prepay |
| Non-indexed, in pesos (like consumer loans) | 1 month of interest on the amount you prepay |
Source: Law 18,010, article 10. Above 5,000 UF, prepayment terms are freely agreed with the bank.
The law adds three important rules:
- On those loans, you can prepay even if the bank does not want you to.
- If the payment is less than 10% of the balance, you do need the bank's approval.
- It is a right that cannot be waived: a contract clause cannot take it away.
How much you could save: an example with numbers
We take a loan of UF 3,000 over 30 years, taken out in December 2023 at that month's average rate (5.21%). After 35 payments, the balance is about UF 2,866 (CLP 118.4 million). If it is refinanced at October 2026's average rate (4.10%) for the remaining term:
| Original loan (5.21%) | Refinanced loan (4.10%) | |
|---|---|---|
| Monthly payment | CLP 672,183 | CLP 598,975 |
| Difference | CLP 73,208 less per month | |
| Maximum prepayment fee | CLP 753,473 | |
| Months to recover the fee | About 10 |
InfoByData calculation with the UF of November 12, 2026 (CLP 41,316.06). Payments without insurance. Does not include the costs of the new loan.
Over the 27 years left on the loan, that difference adds up to about CLP 23.8 million in today's pesos. But the saving depends on how much the rate falls. If your original rate is closer to today's, the benefit shrinks quickly:
| Your current loan's rate | Monthly saving when refinancing at 4.10% | Maximum prepayment fee | Months to recover it |
|---|---|---|---|
| 5.21% | CLP 73,208 | CLP 753,473 | 10 |
| 5.00% | CLP 58,988 | CLP 722,600 | 12 |
| 4.80% | CLP 45,602 | CLP 693,205 | 15 |
| 4.60% | CLP 32,372 | CLP 663,822 | 21 |
| 4.50% | CLP 25,816 | CLP 649,137 | 25 |
Same example: UF 3,000 loan over 30 years with 35 payments made. InfoByData calculations.
Source: Central Bank, Statistical Database
View the data as a table
| Jan 22 | 4.2% |
| Jul 22 | 4.31% |
| Jan 23 | 4.32% |
| Jul 23 | 4.24% |
| Dec 23 | 5.21% |
| Apr 24 | 4.87% |
| Jul 24 | 5.03% |
| Oct 24 | 4.54% |
| Jan 25 | 4.4% |
| Jul 25 | 4.36% |
| Jan 26 | 4.12% |
| May 26 | 3.96% |
| Oct 26 | 4.1% |
People who borrowed between October 2023 and September 2024 paid average rates above 4.7%. That is the group with the most room to refinance a mortgage. Note that the rate has risen from May's low of 3.96%, so the margin could shrink if it keeps rising. We explain it in how mortgage rates have changed.
The other costs of refinancing
The prepayment fee is not the only expense. A new loan usually involves costs for home appraisal, title search, notary and registration with the Real Estate Registrar. Stamp tax has an exemption for loans that pay off another loan, up to the amount of the balance being repaid, according to the SII.
To know whether it pays off, add all those expenses to the fee and divide by the monthly saving: the result is the number of months it takes to recover what you spend. If you plan to sell the home before then, it does not pay off.
How to refinance with financial portability
Law 21,236 on financial portability made switching banks a customer right. The process works like this:
- You request portability from the new bank. It asks your current bank for the settlement certificate with your outstanding balance.
- The new bank makes you an offer. It must detail the products it proposes and the costs and expenses of switching, and remain valid for at least seven banking business days.
- If you accept, the new bank handles the paperwork. It pays off your previous loan and, for mortgages, the law allows the new loan to legally replace the old one (special subrogation), which simplifies the process.
Before switching, ask your current bank to improve its rate. With another bank's offer in hand, you have more bargaining power.
What it means for you
- Compare your rate with today's. It is in your deed or your account statement. If it exceeds the current rate by more than half a point, it is worth getting quotes.
- Get quotes from several banks. The ranking of the best mortgages for November shows standard offers starting at a CAE of 4.52%, with Santander and BancoEstado at the top. You can see all offers in the mortgage comparison tool.
- Do the full math. Refinancing a mortgage pays off if the monthly saving recovers the fee and expenses before you sell or finish paying. The CMF's prepayment calculator helps you estimate the amount.
- If your loan has a benefit, such as a rate subsidy, ask whether you keep it when refinancing.
This article is for information only and is not financial advice.
Sources
- refinancing a mortgage
- prepayment
- prepayment fee
- financial portability
- monthly payment
- interest rates
- CMF