Where to invest in Chile: what returns digital platforms offer compared with inflation
Where to invest in Chile with digital platforms: Copec Pay pays 6% a year, Mercado Pago up to 5% and Tenpo 4.4%, with inflation at 4.5%. We compare them.
· 6 min read
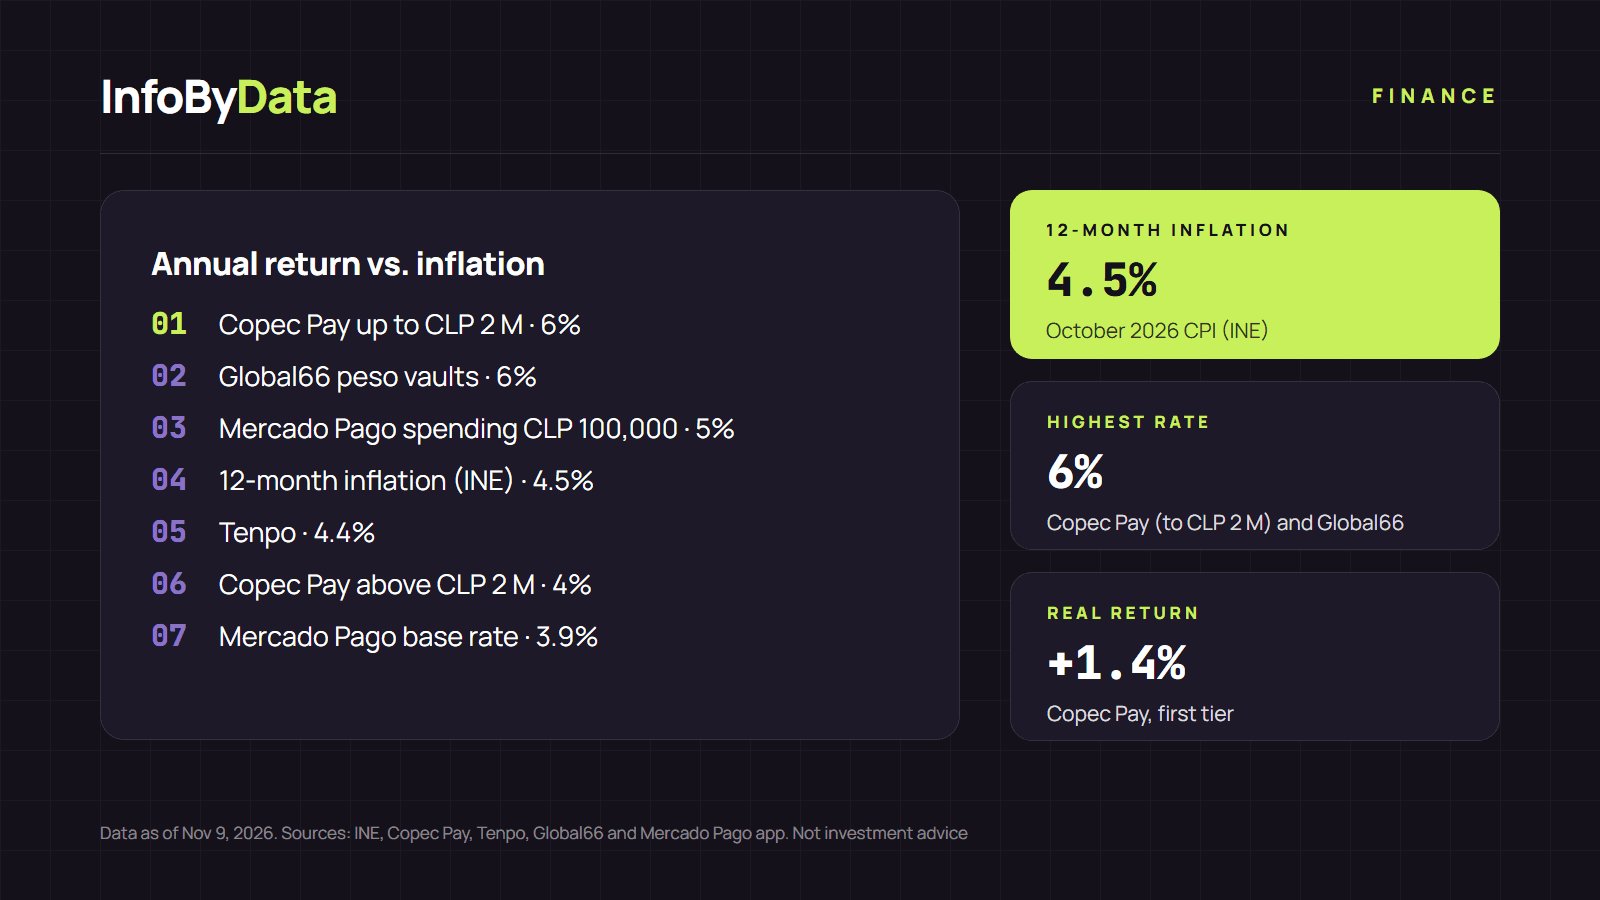
If you are wondering where to invest your savings in Chile, the first benchmark is inflation: according to the INE, Chile's statistics agency, prices rose 4.5% over the 12 months to October 2026. A platform that pays less than that doesn't grow your money in real terms: it only slows its loss. We compare what five popular digital platforms, Copec Pay, Mercado Pago, Tenpo, Global66 and Fintual, offer, using their official rates and conditions.
Data as of November 9, 2026. These platforms change their rates often: all figures in this article are as of that date.
Where to invest with digital platforms: the comparison
| Platform | What it is | Annual return | Approx. real return* | Minimum |
|---|---|---|---|---|
 Copec Pay "Mis Ganancias" |
Interest-bearing account | 6% up to CLP 2 million and 4% on the excess | +1.4% / −0.5% | CLP 40,000 |
 Global66, peso vaults |
Interest-bearing account | 6% (return not guaranteed) | +1.4% | CLP 100,000 average balance |
 Mercado Pago "Haz crecer tu dinero" |
Balance invested in a short-term mutual fund (BICE MP Liquidez) | 3.9% base and 5% if you spend CLP 100,000 in the month | −0.6% / +0.5% | No minimum stated |
 Tenpo Cuenta Remunerada |
Interest-bearing account | 4.4% | −0.1% | CLP 30,000 average balance |
 Fintual |
Mutual funds, variable return | Very Conservative Streep: 4.20%; Risky Norris: 43.50% (12 months to May 11, 2026) | −0.3% / +37.3% | No minimum |
*Real return: how much money grows after 4.5% inflation. It is calculated as (1 + rate) / (1 + inflation) − 1. It is a reference, because it compares today's rate with past inflation.
Copec Pay: the highest rate, with caps
According to its official page, "Mis Ganancias" pays 6% a year on balances between CLP 40,000 and CLP 2,000,000, and 4% a year on anything above CLP 2,000,000. Earnings are calculated daily on the previous day's balance, and are only paid if the total balance does not exceed CLP 20 million. It pays the highest rate, though only in the first tier. The company says it operates under CMF rules.
Tenpo: 4.4% a year
Tenpo's interest-bearing account pays an annual rate of 4.4%. To earn it, the previous day's average balance must be at least CLP 30,000, and earnings are paid every day, including holidays. Withdrawing money during the day reduces the next day's payment.
Mercado Pago: up to 5% if you use the account
According to the Mercado Pago app, accessed on November 9, 2026, "Haz crecer tu dinero" pays a base rate of 3.9% a year, rising to 5% a year if you spend CLP 100,000 in the month. With that condition, it beats inflation; without it, it falls short.
The balance is invested in the BICE MP Liquidez mutual fund, a short-term debt fund run by BICE Inversiones and registered with the CMF, Chile's financial regulator. That is why its return depends on the instruments the fund invests in and can change: according to its factsheet, with data as of July 31, 2026, the fund's series A returned 4.27% nominal over the previous 12 months. The factsheet warns that past returns do not guarantee future ones.
Global66: 6% in pesos, with no guaranteed return
Global66 states on its official site that its "vaults" generate annual returns of 6% in pesos. According to the terms of its interest-bearing account, it is offered by Global Card S.A., requires an average daily balance of at least CLP 100,000 during the month and pays monthly. The same terms state that the return is voluntary and not guaranteed: it gives no right to a minimum return. Global66 also offers a dollar account with a return of up to 6% a year, whose balance is held by 100x Corp. under Panamanian rules.
Fintual: mutual funds with different levels of risk
Fintual is a fund manager regulated by the CMF. It doesn't offer a rate: it invests in mutual funds whose value rises or falls. According to a Fintual post, with data as of May 11, 2026 (series A), its most conservative fund, Very Conservative Streep, returned 4.20% over one year, and its riskiest, Risky Norris, which invests in global stocks, 43.50%. It charges a 1.19% annual fee and has no minimum. Fintual warns that past returns do not guarantee future ones.
Real return: the number that matters
When deciding where to invest, the rate each platform advertises is only half the story. With 4.5% inflation:
- CLP 1,000,000 in Copec Pay (first tier) becomes CLP 1,060,000 in a year. After inflation, you gain about CLP 14,000 in purchasing power.
- CLP 1,000,000 in Tenpo reaches CLP 1,044,000: practically breaking even with inflation.
- CLP 1,000,000 in Mercado Pago reaches CLP 1,050,000 if you meet the spending condition: about CLP 4,800 of purchasing power in your favor. At the 3.9% base rate, however, you lose about CLP 5,700.
October inflation rose on transport (+2.0%) and food (+1.0%), according to the INE. If it falls in the coming months, the real return of these platforms will improve, and vice versa.
What risks they carry: guarantee and liquidity
Before choosing where to invest, check what backs your money:
- Non-bank prepaid accounts: the CMF explains that accounts linked to prepaid payment cards issued by non-bank entities are not covered by the state deposit guarantee in Article 144 of the General Banking Law. As a safeguard, the funds must be kept separate from the company's own resources. Tenpo Payments S.A. and Mercado Pago Emisora S.A. appear in the CMF's register of non-bank issuers.
- Mutual funds: they have no state guarantee either, and their value can rise or fall. The Mercado Pago fund's factsheet rates its risk tolerance as low, since it invests in short-term debt.
- Liquidity: at Copec Pay and Tenpo the balance is available at any time, and the Mercado Pago fund has a redemption period of 1 business day, according to its factsheet. A term deposit, by contrast, locks up the money for the agreed term.
- Global66 and Fintual: Global Card S.A., which offers Global66's peso account, also appears in the CMF's register of non-bank issuers. Fintual's funds are CMF-regulated mutual funds with no state guarantee, and their value can fall, especially in the riskiest ones such as Risky Norris.
- Rates change: the rates of interest-bearing accounts are not fixed. Companies can change them depending on market conditions.
If you are looking for higher returns in exchange for more risk, such as cryptocurrencies, first read our guide to starting to invest in crypto with little money and the risks involved.
What it means for you
- Always compare against inflation. When deciding where to invest, a 4.4% rate sounds good, but with 4.5% inflation your money barely keeps its value.
- Check the tiers and minimums. Copec Pay's 6% only applies up to CLP 2 million, and the accounts require a minimum balance to pay earnings.
- Understand what backs your money. These accounts do not have the state guarantee of bank deposits. This article is for information only and is not investment advice: check each platform's current terms before deciding.
Sources
- INE, Consumer Price Index for October 2026 (November 6, 2026, in Spanish)
- Copec Pay, Mis Ganancias (in Spanish) (accessed November 9, 2026)
- Tenpo, Cuenta Remunerada (in Spanish) (accessed November 9, 2026)
- Global66, dollar account and vaults (in Spanish) and interest-bearing account terms (in Spanish) (accessed November 9, 2026)
- Fintual, fund returns as of May 11, 2026 (in Spanish) and official site
- Mercado Pago app, "Haz crecer tu dinero" rates (accessed November 9, 2026)
- CMF, BICE MP Liquidez mutual fund: factsheet (data as of July 31, 2026)
- CMF, Prepaid payment cards in Chile (in Spanish)
- CMF, non-bank issuers of prepaid payment cards (in Spanish)
- where to invest
- interest-bearing accounts
- Copec Pay
- Mercado Pago
- Tenpo
- Global66
- Fintual
- inflation
- real return