Consumer loans in Chile: how much they cost, what the maximum rate is and which banks lend the most
Consumer loans in Chile: the average rate was 24.57% in October 2026, the legal cap reaches 41.02% and five banks hold 75% of all bank consumer lending.
· 5 min read
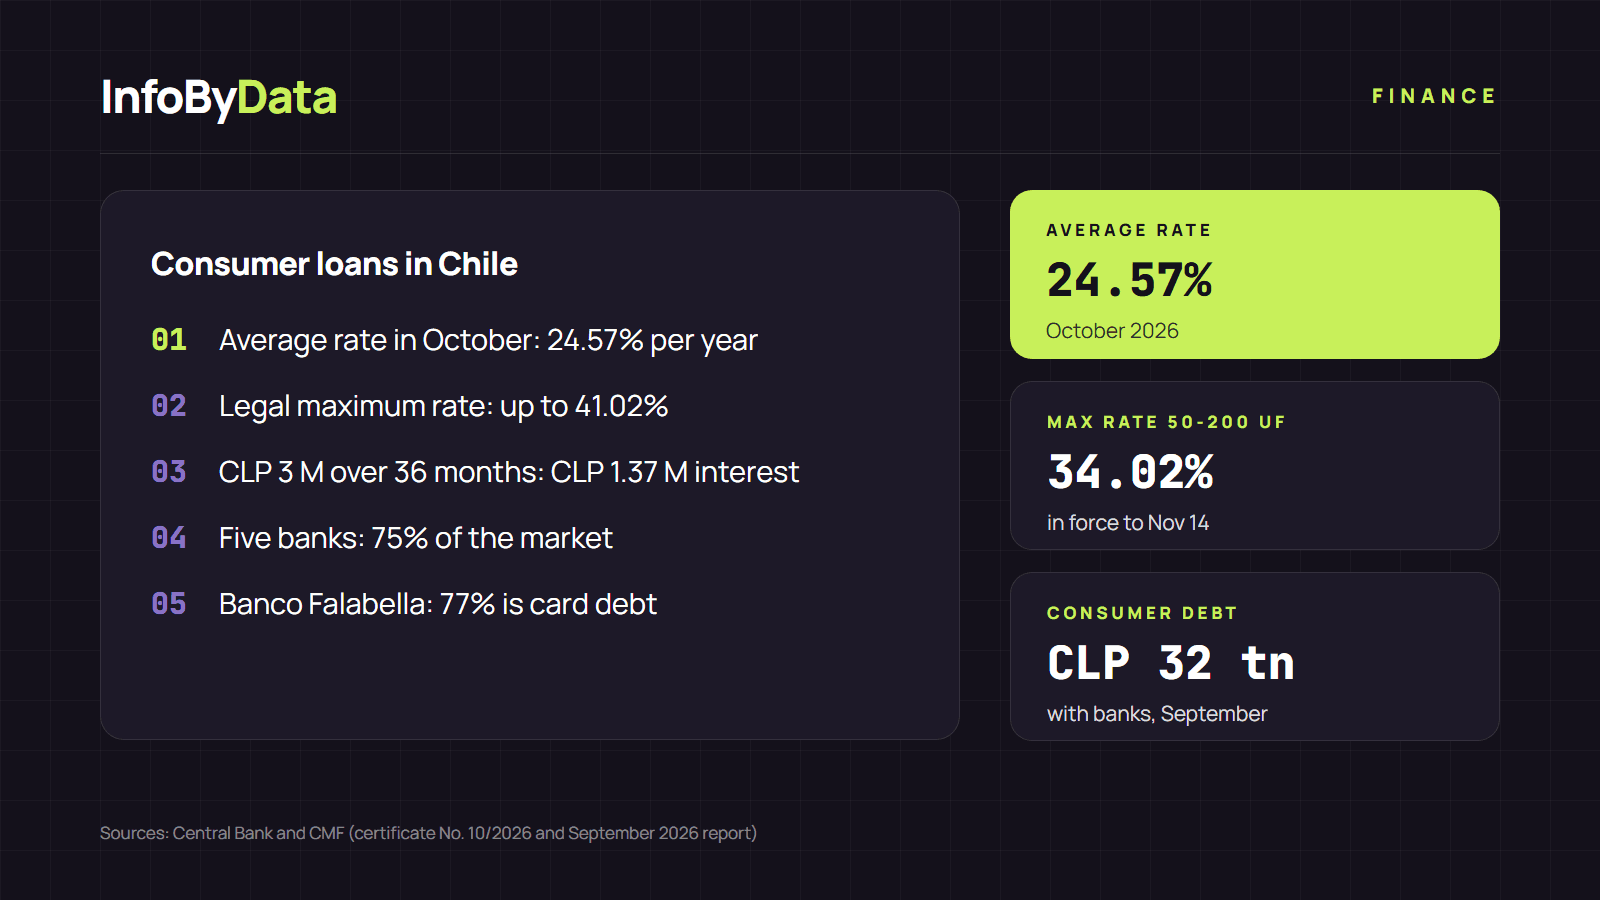
Borrowing money for consumption costs almost six times as much today as a home loan. In October 2026, the average rate on consumer loans in Chile was 24.57% a year, according to the Central Bank. In the same month, the mortgage rate was 4.10%. In this article we look at how much a consumer loan costs, how much a bank is allowed to charge and which institutions dominate the market.
24.57%
Average rate in October
per year, all terms
34.02%
Legal maximum rate (50 to 200 UF)
in force until November 14
CLP 32 trillion
Consumer debt with banks
September 2026
2.65%
Loans more than 90 days overdue
of all consumer loans
Source: Central Bank, CMF, certificate No. 10/2026 and CMF, September 2026 report
View the data as a table
| Average rate in October | 24.57% | per year, all terms |
| Legal maximum rate (50 to 200 UF) | 34.02% | in force until November 14 |
| Consumer debt with banks | CLP 32 trillion | September 2026 |
| Loans more than 90 days overdue | 2.65% | of all consumer loans |
How much consumer loans in Chile cost today
The average consumer loan rate rose during 2026: it went from 23.41% in January to a peak of 26.00% in July, and fell to 24.57% in October. A year earlier, in October 2025, it was 23.01%.
Source: Central Bank, Statistical Database, total consumer
View the data as a table
| Jan 25 | 24.54% |
| Mar 25 | 23.35% |
| May 25 | 24.19% |
| Jul 25 | 24.01% |
| Sep 25 | 23.8% |
| Nov 25 | 23.62% |
| Jan 26 | 23.41% |
| Mar 26 | 23.39% |
| May 26 | 25.61% |
| Jul 26 | 26% |
| Sep 26 | 25.86% |
| Oct 26 | 24.57% |
The rate varies a lot with the term. Loans of less than six months have the lowest rate, and those of six months to one year, the highest:
Why does a consumer loan cost so much more than a mortgage? The main reason is risk. A mortgage is secured by the home; a consumer loan is not. According to the CMF, banks hold provisions for 8.24% of their consumer portfolio to cover possible losses, compared with just 0.63% of their housing portfolio.
An example: how much you pay for CLP 3 million
At October's average rate for one- to three-year loans (26.25%), a loan of CLP 3,000,000 is repaid like this, counting interest only:
| Term | Monthly payment | Total paid | Interest |
|---|---|---|---|
| 24 months | CLP 162,002 | CLP 3,888,053 | CLP 888,053 |
| 36 months | CLP 121,272 | CLP 4,365,783 | CLP 1,365,783 |
| 48 months | CLP 101,574 | CLP 4,875,568 | CLP 1,875,568 |
InfoByData calculation using the Central Bank's average rate for 1- to 3-year loans (October 2026). It does not include insurance, fees or stamp tax, which raise the final cost.
A longer term lowers the payment but makes the loan more expensive: going from 24 to 48 months cuts the payment by CLP 60,428, but adds almost CLP 1 million more in interest.
What is the maximum rate you can be charged
In Chile, no loan can exceed the maximum conventional rate (TMC), which the CMF publishes every month in the Official Gazette. For peso loans of 90 days or more, the cap depends on the amount:
| Loan amount | Maximum rate (TMC) | Current rate (reference average) |
|---|---|---|
| Up to 50 UF (about CLP 2.07 million) | 41.02% per year | 32.82% per year |
| Over 50 and up to 200 UF (about CLP 8.26 million) | 34.02% per year | 29.56% per year |
| Over 200 and up to 5,000 UF | 30.03% per year | 20.02% per year |
Source: CMF, certificate No. 10/2026, published in the Official Gazette on October 15, 2026 and in force until November 14. UF on November 12, 2026: CLP 41,316.06. The CMF publishes a new certificate every month.
The smaller the loan, the higher the legal cap. At the TMC for the 50 to 200 UF bracket (34.02%), the same CLP 3,000,000 loan over 36 months would have a payment of CLP 134,049 and you would pay CLP 1,825,777 in interest, CLP 460,000 more than at the average rate.
Which banks lend the most in consumer loans
As of September 2026, banks had CLP 32.04 trillion in consumer loans outstanding, according to the CMF. That is 1.56% less than a year earlier, after inflation. Five banks hold 75% of the total:
There are two different models. At traditional banks, most consumer lending is installment loans. At banks linked to retailers, it is the other way around: 77% of Banco Falabella's consumer portfolio and 91% of Banco Ripley's is credit card debt.
Delinquency also varies. 2.65% of the banks' consumer portfolio is more than 90 days overdue. The highest rates are at Banco Ripley (3.48%), BancoEstado (3.29%) and Scotiabank (3.25%); the lowest, at Banco Internacional (1.40%), Banco Consorcio (1.43%) and Banco Bice (1.44%). You can see how banks compare on other indicators in banks in Chile in figures.
How to compare consumer loans in Chile
- Compare the CAE, not the rate. The annual equivalent charge (CAE) adds up the rate, insurance and fees in a single percentage. Banks must report it in their quotes.
- Ask for the total cost of the loan. It is the sum of all payments: it shows how much you will really pay.
- Check the insurance attached. It raises the payment: ask which policies are mandatory and which you can decline.
- Prepaying has a capped cost. For peso loans of up to 5,000 UF, the prepayment fee cannot exceed one month of interest on the amount you pay early, under article 10 of Law 18,010. We explain how it works in prepaying or refinancing a mortgage.
What it means for you
If you plan to use a consumer loan to pay part of the down payment on a home, do the full math: at today's rates, that loan can cost you more than the mortgage itself. Before deciding, check the ranking of the best mortgages for November, where the CAE starts at 4.52%.
Consumer loans in Chile are expensive because they are unsecured, and the term, the amount and the insurance can change the final cost a lot. Get quotes from at least three institutions and compare the CAE and the total cost. This article is for information only and is not financial advice.
Sources
- Central Bank of Chile, Statistical Database: consumer lending rates (data to October 2026)
- Central Bank of Chile, UF housing lending rates
- CMF, certificate No. 10/2026 on current and maximum conventional interest rates (Official Gazette, October 15, 2026)
- CMF, Monthly Financial Information Report on the Banking System, September 2026
- Law 18,010, article 10, BCN
- SII, UF values 2026
- consumer loans in Chile
- consumer loan
- maximum conventional rate
- CAE
- banks
- CMF
- Central Bank