Income needed for a mortgage in Chile: how much you have to earn with and without a subsidy
The income needed for a mortgage on a UF 4,000 home is about CLP 2.9 million without a subsidy. How much it drops with the rate subsidy and the DS1 subsidy.
· 4 min read
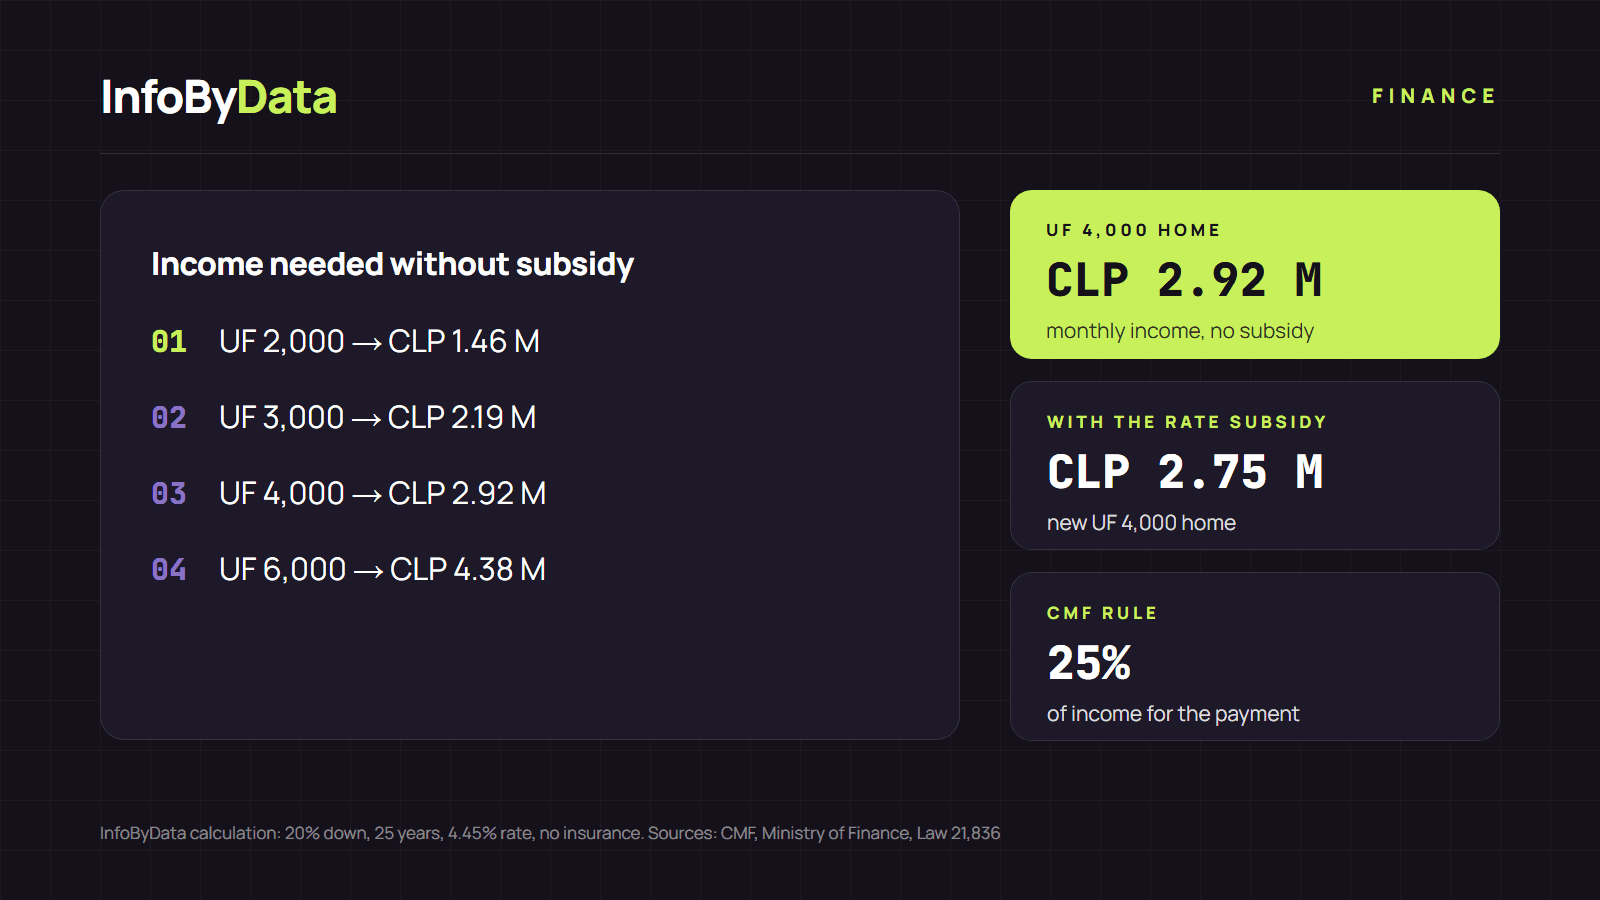
The income needed for a mortgage depends on the monthly payment you will make. The CMF, Chile's financial regulator, notes that several institutions recommend that the payment be at most 25% of the total income of the borrower, or of the borrower and their co-signer. With that rule, for a UF 4,000 home without a subsidy you need to earn about CLP 2.9 million a month. The UF (Unidad de Fomento) is Chile's inflation-indexed unit of account. With a subsidy, the figure can drop considerably.
CLP 2.92 M
UF 4,000 home without subsidy
monthly income
CLP 2.75 M
With the rate subsidy
new home
CLP 1.01 M
DS1 bracket 2 (UF 1,600 home)
monthly income
Source: InfoByData calculation with the CMF 25% rule, a 4.45% rate and the UF of November 6, 2026
View the data as a table
| UF 4,000 home without subsidy | CLP 2.92 M | monthly income |
| With the rate subsidy | CLP 2.75 M | new home |
| DS1 bracket 2 (UF 1,600 home) | CLP 1.01 M | monthly income |
How the income needed for a mortgage is calculated
If the payment should not exceed 25% of your income, the math is simple: the income you need is your payment multiplied by 4. Keep three things in mind:
- You can combine incomes: the bank can add another person's income, and that person submits the same documents.
- Your debts count against you: the CMF recommends subtracting fixed expenses and other installments, such as purchases on credit, from your income.
- Each bank runs its own assessment: 25% is a recommendation, not a legal rule.
For the calculations in this article we use a 25-year loan and the banks' reference rate for November 2026 (4.45%), set by the Ministry of Finance. Payments exclude insurance and use the UF of November 6 (CLP 41,279.51, according to the SII).
Income needed for a mortgage without a subsidy
With a 20% down payment (the bank finances up to 80%), this is the income needed by home value:
| Home value | 20% down payment | Monthly payment | Income needed |
|---|---|---|---|
| UF 2,000 | CLP 16.5 million | CLP 365,240 | CLP 1,460,960 |
| UF 3,000 | CLP 24.8 million | CLP 547,860 | CLP 2,191,440 |
| UF 4,000 | CLP 33.0 million | CLP 730,480 | CLP 2,921,920 |
| UF 6,000 | CLP 49.5 million | CLP 1,095,720 | CLP 4,382,880 |
On top of the down payment, you need money for notary, registrar and tax costs. We detail them in the requirements to apply for a mortgage.
With the rate subsidy: how much the income drops
The mortgage rate subsidy cuts the rate by up to 0.6 points for buyers of a new home, in its first sale, worth up to UF 6,000. It runs until May 31, 2028, and the bank handles it. With a 3.85% rate (4.45% minus 0.6 points), the income needed drops like this:
- Without subsidy
- With rate subsidy
Source: InfoByData calculation with 20% down, 25 years, 4.45% and 3.85% rates, no insurance; Law 21,836
View the data as a table
| Without subsidy | With rate subsidy | |
|---|---|---|
| UF 3000 | 2,191,440 | 2,059,048 |
| UF 4000 | 2,921,920 | 2,745,397 |
| UF 6000 | 4,382,880 | 4,118,095 |
On a UF 4,000 home, the subsidy reduces the income needed for a mortgage by CLP 176,523 a month. We explain its conditions in our article on the 4,000 UF subsidy.
With the DS1 subsidy: a smaller loan
The Housing Ministry's DS1 subsidy pays part of the home's price. That way, the loan you take is smaller and so is the income you need. These are the calculations with the subsidy and minimum savings of each bracket:
| DS1 bracket | Home | Subsidy + savings | Loan | Income needed |
|---|---|---|---|---|
| Bracket 2 | UF 1,600 | UF 450 + UF 40 | UF 1,110 | CLP 1,013,541 |
| Bracket 3 | UF 2,200 | UF 270 + UF 80 | UF 1,850 | CLP 1,689,235 |
| 4,000 bracket | UF 4,000 | UF 400 + UF 200 | UF 3,400 | CLP 3,104,540 |
For brackets 2 and 3 we use the average subsidy reported by ChileAtiende; the actual amount varies by case. The 4,000 bracket has a fixed subsidy of UF 400 in central and southern Chile, according to ChileAtiende.
In the 4,000 bracket, the income is similar to a purchase without a subsidy, but the big difference is the down payment: you put in UF 200 of savings (about CLP 8.3 million) instead of a UF 800 down payment (about CLP 33 million).
Note: bracket 3 also has an income cap
If your Social Household Registry (RSH) score is above 90%, your household income cannot exceed these amounts to apply for bracket 3, according to the Housing Ministry (Minvu):
| Household members | Maximum net household income (Santiago and Coquimbo to Los Lagos) |
|---|---|
| 1 person | CLP 1,992,086 |
| 2 people | CLP 2,788,921 |
| 3 people | CLP 3,107,655 |
| 4 or more | CLP 3,426,388 |
In the extreme regions the cap is higher.
Calculate your own case with the home value, down payment and rate you are offered:
What it means for you
- Calculate your income before house hunting. Multiply the payment by 4 to see if it fits, and subtract your current debts.
- If your income falls short, you have options. You can combine incomes with another person, pay off debts before applying or look for a home that qualifies for a subsidy.
- Check whether you qualify for a subsidy. The rate subsidy lowers the income needed, and the DS1 lowers the loan and the down payment. The calculations in this article are illustrative and are not financial advice: each bank assesses your case.
Sources
- CMF Educa, do I have the repayment capacity for a mortgage? (in Spanish)
- Ministry of Finance, reference rates for November 2026 (Official Gazette)
- Law 21,836, Official Gazette of August 17, 2026
- ChileAtiende, DS1 bracket 2, bracket 3 and new 4,000 bracket
- Minvu, first national call of 2026 for the DS1
- SII, UF values 2026
- income needed for a mortgage
- mortgage
- monthly payment
- rate subsidy
- DS1 subsidy
- repayment capacity